
Facilities management projects rarely fail because people are not working hard enough.
They fail because the wrong decision was taken before the work properly began. DICE is the discipline EMC uses to prevent that, and this is how it works in practice.
Facilities management projects rarely fail through lack of effort. They fail because a decision was made early, on incomplete evidence, and everything that followed was an attempt to deliver it well.
A contract is retendered because costs have risen, but nobody has established whether the increase is being driven by scope, labour, indexation, supplier margin, a poor original specification, operational drift or genuine market movement. A supplier is replaced because performance has slipped, while the contract that rewarded the wrong behaviours is carried forward unchanged into the new arrangement. A specification is rewritten because the service does not feel right, although the data behind service levels, volumes, frequencies and risk has never been properly interrogated. A benchmarking exercise is commissioned and delivers a spreadsheet, without ever explaining what the numbers actually mean or what the organisation should do about them.
In each case the organisation has moved to the answer before it has understood the problem. In a market under pressure from rising labour costs, tightening compliance obligations, ageing estates, changed workplace patterns and constrained budgets, that approach is no longer defensible. Facilities management leaders need more than opinion, more than supplier reassurance and more than a conventional procurement process. They need a structured way of reaching a decision that will survive scrutiny.
That is why EMC works to DICE, which stands for Discover, Investigate, Challenge and Execute. It is the structure behind our forensic benchmarking, tender management, contract review, PFI advisory, catering consultancy and supplier performance work, and its purpose is to ensure that a recommendation follows the evidence rather than a preferred solution arrived at in advance.
Discover: establish the real starting point
Every successful facilities management project begins with an accurate understanding of the current position. Not the position described in monthly reports, nor the version presented in supplier review meetings, nor the version implied by the contract file, but the position as it genuinely stands.
That means examining the full picture, including contracts, specifications, service scopes, invoices, variation history, key performance indicators, helpdesk data, compliance records, staffing models, asset information, user feedback, supplier obligations and stakeholder expectations. It also means being explicit about what success actually looks like for this organisation, because the answer is not the same in every case. For one client it may mean reducing cost without creating compliance exposure. For another it may mean improving workplace experience, rebuilding supplier accountability, stabilising a catering operation, preparing properly for retender, or establishing whether a legacy PFI arrangement still represents value.
The Discover phase answers the questions that are too often skipped at the beginning of a project. What are we paying for, and what are we actually receiving. Where is performance strong, where is it weak, and where is it simply unclear. Which risks are visible in the reporting, and which are buried in the contract. How has the service changed since the original agreement was signed, and does the organisation still need what it asked for five years ago.
Without that foundation every subsequent decision is exposed. Procurement becomes an exercise in informed guesswork, benchmarking becomes superficial, contract management becomes reactive, and supplier challenge becomes very difficult because the client does not hold the evidence required to sustain a position. Discovery is not administration, it is commercial protection.
The FM audit is what discovery looks like in practice
In most engagements the mechanism that delivers the Discover phase is a structured facilities management audit, and it is worth being specific about what that involves, because the term is used loosely across the sector.
A proper audit verifies rather than accepts. It establishes and validates the asset register, including condition and criticality, rather than relying on a list inherited from a previous supplier or a mobilisation exercise that was never revisited. It measures and confirms the volumetric base, covering cleanable areas, occupied hours, covers, helpdesk volumes and consumption, against the assumptions embedded in the current pricing model. It examines the labour establishment being paid for against the establishment actually deployed, and tests applied rates against current National Living Wage and sector pay settlements. It reviews the compliance position, distinguishing between what has been asserted, what has been evidenced and what is genuinely outstanding. It reconstructs the financial position, covering indexation applied against indexation contractually due, mark-ups on consumables and materials, margin taken on subcontracted work, overhead recovery, and deductions earned against deductions actually taken.
The output is a documented and defensible baseline. That baseline is the single most valuable asset a client organisation can hold going into a benchmarking exercise, a renegotiation, a retender or a PFI expiry discussion, and it is the thing that most organisations discover they do not have at precisely the moment they need it.
Investigate: find the cause rather than the symptom
Once the facts are established, the consultancy work properly begins. The purpose of investigation is not to confirm that costs are high, service levels are inconsistent or user satisfaction is poor, because the organisation almost always knows that already. The purpose is to establish why.
Why are cleaning costs above those of comparable estates. Why is maintenance expenditure rising faster than the indexation rate would suggest. Why are performance indicators being achieved while users remain dissatisfied. Why do variations keep appearing. Why is a catering contract underperforming commercially despite apparently strong footfall. Why does a supplier insist the contract is underfunded when the client is confident it is paying enough.
Those questions cannot be answered by headline benchmarking. A meaningful benchmark has to go beneath the number and account for specification, site complexity, opening hours, labour model, geography, risk transfer, asset condition, compliance burden, contract maturity, reporting quality and supplier behaviour. That is the distinction between ordinary benchmarking and forensic benchmarking. Ordinary benchmarking establishes that a cost is higher than average. Forensic benchmarking establishes whether it is higher because the service is genuinely more complex, because the specification has become inflated, because the supplier has priced in risk it is not actually carrying, because contract controls are weak, or because the market has simply moved.
Forensic benchmarking in practice
The following example is a composite, drawn from patterns that recur across the sector rather than from any single engagement, but the shape of it will be familiar to anyone who has run this work.
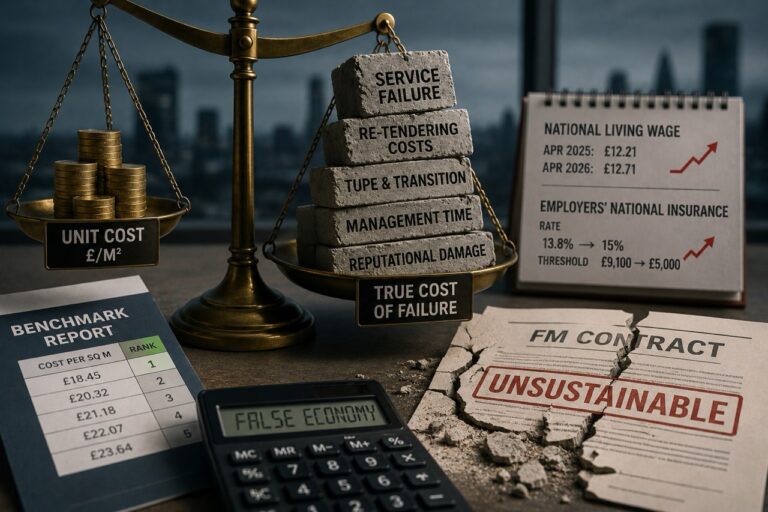
A client benchmarks its cleaning contract and finds it sitting some eighteen per cent above comparable estates. On an ordinary benchmark that finding leads directly to a conclusion, which is that the contract is expensive and should be retendered. A forensic review produces a considerably more useful picture, because the eighteen per cent turns out to be four separate things wearing the same coat.
A meaningful proportion of the gap is specification. The schedule still prices daily servicing for a floor that was mothballed eighteen months earlier and for meeting rooms whose usage has fallen away, so the client is buying a service it no longer consumes. A second element is genuine and sits with the supplier, because a fit-out changed the building from open plan to substantially cellular, and the productivity rate embedded in the original pricing model no longer reflects what can realistically be achieved, meaning the supplier is legitimately carrying hours the model does not recognise. A third element is recoverable, because consumables are being charged at a mark-up that was never tested and indexation has been applied annually to the whole contract sum including a management fee that the contract states should be fixed. Only the fourth element, and by some distance the smallest, is a genuine gap against the market.
The commercial consequences of that distinction are considerable. Had the client proceeded straight to retender on the ordinary benchmark, it would have taken an inflated specification to market, received bids that appeared competitive against a baseline that was wrong, and carried the scope error into a fresh five-year commitment. It would also have abandoned a recoverable position rather than settling it, and it would have created a contract in which the supplier was once again pricing a productivity assumption that does not match the building. The forensic route produces four different actions, only one of which is a price conversation.
Challenge: test the assumptions before the market does
One of the more persistent obstacles to better facilities management performance is the observation that this is how it has always been done, and the Challenge phase exists to subject that thinking to proper scrutiny.
Does the service specification still reflect how the building is actually used. Are cleaning frequencies aligned to real occupancy and risk rather than to a historic pattern. Is the maintenance strategy properly aligned to statutory obligation and to recognised standards such as SFG20. Are the performance indicators measuring meaningful outcomes, or are they measuring supplier activity that is easy to report. Are catering subsidies delivering value or concealing a weak commercial model. Is the procurement route proportionate to the complexity of the service. Do the contract incentives encourage the behaviours the organisation actually wants. Is technology improving control, or has it simply added another reporting layer. Are stakeholders requesting improvements without any visibility of the cost consequences.
This is the point at which independence matters most. A good adviser should neither validate the client existing view by default nor arrive with a predetermined answer, and the role is to challenge every party to the discussion, including the client assumptions, the supplier explanations and the comfortable answers the market offers. Sometimes the right recommendation is a competitive tender. Sometimes it is renegotiation, a contract reset, better governance, clearer reporting, stronger performance management or a revised specification. Sometimes the uncomfortable conclusion is that the organisation is asking for a standard of service that its budget cannot realistically support, and saying so early is considerably more useful than discovering it during mobilisation.
This matters particularly in facilities management, where procurement is frequently treated as the default response to dissatisfaction. Retendering is not always the answer. Where the underlying problem is poor scope, weak data, unclear performance measurement or limited client-side control, those issues will reappear under a different supplier badge within eighteen months. Challenge protects the organisation from solving the wrong problem elegantly.
Where value actually comes from
Adding value in facilities management is often assumed to mean reducing cost, and cost reduction is certainly part of it. The more substantial gains, however, usually come from correcting the relationship between what is being paid for, what is being delivered and what the organisation is actually exposed to. Two further composite examples illustrate the point.
In the first, a client sees maintenance expenditure rising at around nine per cent annually against contractual indexation of roughly three per cent, and the supplier attributes the difference to an ageing plant inventory. Investigation shows that the planned maintenance schedule was inherited from an asset list assembled at original mobilisation and has never been re-mapped against SFG20 criticality classifications. A substantial share of scheduled tasks sits against non-critical assets at frequencies matching those applied to statutory items, while several life-safety systems are being serviced at intervals below the recommended standard. Reactive expenditure, unsurprisingly, is concentrated on exactly those under-maintained critical systems. Rebalancing the regime reduces total planned task volume, redirects attention to statutory and life-safety plant, and lowers reactive callouts. The cost saving is real, but the more significant outcome is the removal of a statutory exposure the organisation did not know it was carrying, and that is value of a kind no headline price comparison would ever have surfaced.
In the second, a catering contract reports healthy footfall while the caterer requests a subsidy that the client believes should not be necessary. Investigation establishes that capital invested at mobilisation is being amortised against a trading account modelled on a five-day attendance pattern, whereas actual attendance is concentrated across the middle of the week, so a fixed labour establishment sized to open five days is being carried against three days of meaningful trade. It also emerges that the client own hospitality booking policy permits departments to procure catering externally, which has quietly removed the highest-margin revenue from the contract. The remedy is partly commercial, involving a more flexible labour model, a revised opening pattern and a reconsidered amortisation profile, and partly a matter of client-side policy. Neither party could have resolved it alone, and a retender would simply have delivered a new supplier into identical economics.
Execute: turn advice into measurable outcomes
Insight creates value only when it is implemented, and this is the stage at which a great many consultancy projects lose momentum. A report is produced, recommendations are agreed, the logic is accepted, and then operational pressure reasserts itself, internal ownership becomes blurred and the opportunity gradually fades.
The Execute phase is designed to prevent that, by converting analysis into a stronger specification, a defensible tender process, a clearer commercial model, an improved contract management regime, a supplier improvement plan, a mobilisation programme or a renegotiated agreement. In a procurement context that may mean supporting a tender from strategy through to award, building pricing schedules that permit genuine comparison between bidders, creating evaluation criteria that test quality, risk and deliverability rather than rewarding the most optimistic submission, challenging supplier responses, managing clarification, supporting negotiation and preparing the organisation for mobilisation. In an existing contract it may mean tightening governance, resetting performance indicators, improving reporting, identifying recoverable value, reducing avoidable variation and establishing a more disciplined supplier review process.
The principle is straightforward, in that recommendations have to translate into measurable improvement, whether that improvement takes the form of better service quality, stronger supplier accountability, clearer commercial control, reduced risk, improved governance or simply greater confidence in the decisions being taken. A report that sits on a shelf has not delivered value, it has only described the possibility of it.
Where the audit earns its place in procurement
The role of the facilities management audit within a procurement process deserves particular attention, because it is the element most frequently omitted and the one whose absence proves most expensive.
Consider a tender taken to market without one. The specification is largely carried forward from the previous contract. The asset register is incomplete and has not been verified. Cleanable areas have not been measured since the original letting. Employment and establishment data has been provided by the incumbent and accepted without validation. The compliance position has been asserted rather than evidenced. Faced with that information, bidders behave rationally and in one of two ways. The cautious ones load contingency to cover risk they cannot quantify, which inflates every price the client receives. The aggressive ones price optimistically on the assumption that the gaps will be recovered later through variations, which produces a submission that wins on price and then unwinds during the contract. Either way the evaluation panel is comparing submissions built on materially different assumptions, so the comparison is not like for like, and the variation register opens within the first quarter of the new contract.
Now consider the same tender preceded by a structured audit. Bidders receive a verified asset register with condition and criticality, measured and validated areas and volumes, reliable establishment and employment information, a documented compliance position that distinguishes evidenced delivery from assertion, and a clear performance baseline. Every bidder is pricing the same thing, so contingency falls out of the pricing and the evaluation can concentrate on deliverability, method and risk rather than on decoding what each bidder has assumed. The client is also in a position to challenge an optimistic submission with evidence rather than instinct, which is the only form of challenge that survives a clarification meeting.
The benefit does not stop at award. The audit baseline becomes the reference point against which the incoming supplier is mobilised and subsequently managed, which means the client-side team begins the contract holding an independent record of what was promised and what the position was on day one. That is precisely the evidence base that organisations struggle to reconstruct three years later when performance has drifted and the original knowledge has left the organisation.
The timing follows from all of this. Audit work belongs somewhere between twelve and twenty-four months ahead of the decision point, which is early enough for the findings to shape the procurement strategy itself, early enough to correct a specification before it goes to market, and early enough that renegotiation remains a genuine alternative to competition if the evidence points that way. An audit commissioned once the tender is already in preparation can still improve the documentation, but it has lost most of its strategic value.
Why this matters now
The sector is operating in a considerably more demanding environment than it was even a few years ago. Budgets are constrained while expectations have not moderated. Buildings are more complex and compliance obligations more visible. Labour availability remains difficult and labour cost continues to rise. Workplace attendance patterns have changed permanently and catering models are being tested as a result. Clients want flexibility while suppliers need certainty, and procurement teams are expected to deliver value while frequently inheriting poor data and ageing specifications.
Transparency has increased as well. Contracts above five million pounds must now carry published key performance indicators, with performance published annually, and contract modifications require a published change notice. Decisions that were once internal are increasingly visible, and the reasoning behind them is increasingly capable of being examined after the event. In that environment an organisation needs to know with some precision whether it has a cost problem, a performance problem, a contract problem, a supplier problem, a data problem or a governance problem, because those are not the same thing and treating them as though they were is one of the more reliable ways to waste a procurement cycle.
The point is not simply better procurement
DICE is not a tender process with a more memorable name. It is a way of approaching facilities management decisions commercially, and forensic benchmarking, tender management, contract review, PFI advisory, catering consultancy and supplier performance improvement all depend on the same underlying discipline. Understand the evidence, identify the drivers, challenge the assumptions and then implement the right solution.
That discipline matters because the best facilities management outcomes very rarely come from chasing the lowest price. They come from understanding what value should look like for this organisation, what it genuinely needs, what the market can realistically deliver at that price, and how the contract will be managed once the decision has been taken. The most expensive mistakes in this sector are made well before the tender is issued, before the supplier is appointed and before the recommendation reaches the board. They are made at the point where an organisation accepts incomplete data, a vague specification, weak performance measures, untested assumptions or a supplier explanation that has never been commercially challenged.
The purpose of DICE is to give facilities management leaders, estates teams, procurement professionals and finance directors a clearer basis on which to decide. It brings structure to complexity, connects operational reality to commercial analysis, and moves an organisation from opinion towards evidence. In the current market that is not a refinement, it is the difference between a decision that looks correct on paper and one that performs in practice.
Is your FM contract delivering what it should?
Book a free discovery call with an EMC consultant. Evidence led, no obligation.
Book a call with EMC
Tell us a little about your FM arrangements and we will come back within one working day to arrange a time.