The Refurbishment Is Free Until the Footfall Is Not
Contractor-funded capital underpins a large share of catering and facilities management contracts across higher education, healthcare and the workplace. It works well, until the revenue line that repays it fails to appear.
A run of higher education catering awards announced this month, worth around £37m across three institutions, carried terms of between five and seven years. To anyone outside the sector that looks like an unusually long commitment for a service that could in principle be re-competed far more frequently. Inside the sector the explanation is well understood and largely uncontroversial, because in a significant proportion of these arrangements the incoming contractor is funding the capital.
Serveries are rebuilt, retail and coffee units are fitted out, kitchen equipment and point-of-sale systems are replaced, and none of it appears in the client organisation capital programme. The cost is recovered instead from the trading account across the life of the contract. The term length is therefore not primarily a judgement about how long the service arrangement should run, but an amortisation period. The arrangement is entirely sound in principle, and it rests on a single condition, which is that the revenue against which the repayment was modelled actually materialises.
A financing decision wearing a service contract
It is worth being precise about what contractor-funded capital actually is, because the language used around it tends to obscure the mechanics. The contractor is not making a gift, and it is not absorbing the cost as a gesture of goodwill. It is advancing capital which it fully expects to recover, together with a return, through the commercial terms of the contract. Recovery may be structured as a fixed annual charge against the trading account, as an adjustment to the management fee, as a share of turnover, or through some combination of the three, but the underlying effect is the same in every case.
This makes the capital element a financing transaction that happens to be embedded within a service agreement, and it deserves the governance that any financing transaction would normally attract. In practice it rarely receives it. The capital offer is typically evaluated during the tender as a benefit rather than as a liability, scored favourably on the basis of its headline value, and then largely forgotten about until something goes wrong.
The implied cost of that finance is the first thing worth interrogating. Because the recovery is bundled into commercial terms rather than expressed as a rate, the effective interest embedded within it is seldom calculated, and where organisations have done the arithmetic the result is often well above what they could have borrowed at directly. For a client with access to capital, the honest comparison is not between spending money and spending nothing, but between the capital cost of funding the works directly and the whole-life cost of having somebody else fund them.
The condition that has to hold
The model performs exactly as intended while volumes hold up. Sales support the trading account, the trading account services the amortisation, the client enjoys refurbished facilities it did not have to fund from its own resources, and the contractor earns an acceptable return on capital it was willing to put at risk. There is nothing objectionable about any part of that, and a great many of these arrangements run their full term without difficulty.
The problem arises when the revenue line underperforms, because the unamortised balance does not adjust itself downwards to match. It remains outstanding and it has to be recovered from somewhere. What follows is a sequence that will be familiar to anyone who has managed a contract through a sustained downturn in volume. Prices rise faster than the client expected. Opening hours contract and units close on the quieter days. Labour on the servery thins out, the range narrows, and the quality of the offer quietly declines. A contract tendered on a nil-subsidy basis eventually produces a request for subsidy, a variation, or a wholesale renegotiation of the commercial terms.
Client organisations very often experience all of this as a deterioration in service accompanied by a stream of awkward commercial requests, without ever connecting it back to a capital schedule agreed at the point of award. The two are frequently the same problem observed from different ends.
Why the volume risk is unusually acute at present
This matters considerably more now than it did five years ago, because the volume assumptions underpinning these arrangements have become much harder to make with any real confidence, and that is true across every sector in which contractor-funded capital is common.
In higher education the pressure is immediate and well documented. Close to half of providers in England are projecting operating deficits for 2025 to 2026, and on a flat international recruitment scenario cumulative sector losses could reach £2.7bn by 2028 to 2029. Campus attendance patterns remain contested, course closures remove entire cohorts from a catchment, and student spending power has been squeezed hard enough to change on-site purchasing behaviour. There is an uncomfortable correlation at work here, in that the institutions least able to fund capital themselves, and therefore most attracted to contractor funding, are frequently the same institutions whose future population is hardest to underwrite.
In the workplace and the wider private sector the mechanism is identical and the exposure is arguably greater still. Hybrid working has permanently altered the relationship between headcount and covers, and a pattern of quiet Mondays and busy Wednesdays makes a weekly average a poor foundation for a seven-year financial model. Reported declines in meals served per employee at corporate sites against pre-pandemic levels have been substantial, and while newer formats such as micro markets, grab-and-go and event-led provision have grown strongly, they generate a very different revenue profile from the traditional staff restaurant that much of the installed capital was originally designed to serve.
Contractors are meanwhile absorbing significant cost pressure of their own. The April 2026 increase in the National Living Wage, continued food inflation in specific categories, and higher business rates all bear on the same trading account from which the capital is being repaid. Sector-level sales growth has remained strong, which can obscure what is happening at individual unit level, and a caterer performing well across a portfolio may still be carrying sites where the amortisation is no longer comfortably covered.
The exit problem
The most significant consequence of contractor-funded capital is one that clients tend to discover only at the moment they want to act. Caterers and facilities management providers expect to recover a proportion of their unrecovered investment if a contract ends early, and that expectation is reflected throughout the commercial terms, particularly within profit and revenue share arrangements.
The practical effect is that the client ability to leave is at its weakest precisely when performance is at its worst, because early termination crystallises the outstanding balance and converts a deteriorating service into an immediate cash demand. An organisation that would otherwise go back to market finds that doing so carries a settlement cost it had never budgeted for, and so it stays. The contract continues, the relationship deteriorates further, and the leverage sits almost entirely on one side of the table.
This is not sharp practice on the part of contractors, and it is important to be fair on that point. A supplier that has advanced capital in good faith is fully entitled to recover it. The failure sits on the client side, in accepting a financing structure whose exit consequences were never modelled, and very frequently never even quantified, at the point the contract was signed.
What good practice looks like
None of the remedies are complicated, and none of them require a client organisation to reject contractor funding. They require only that the capital element is recognised and governed as the financing decision it actually is.
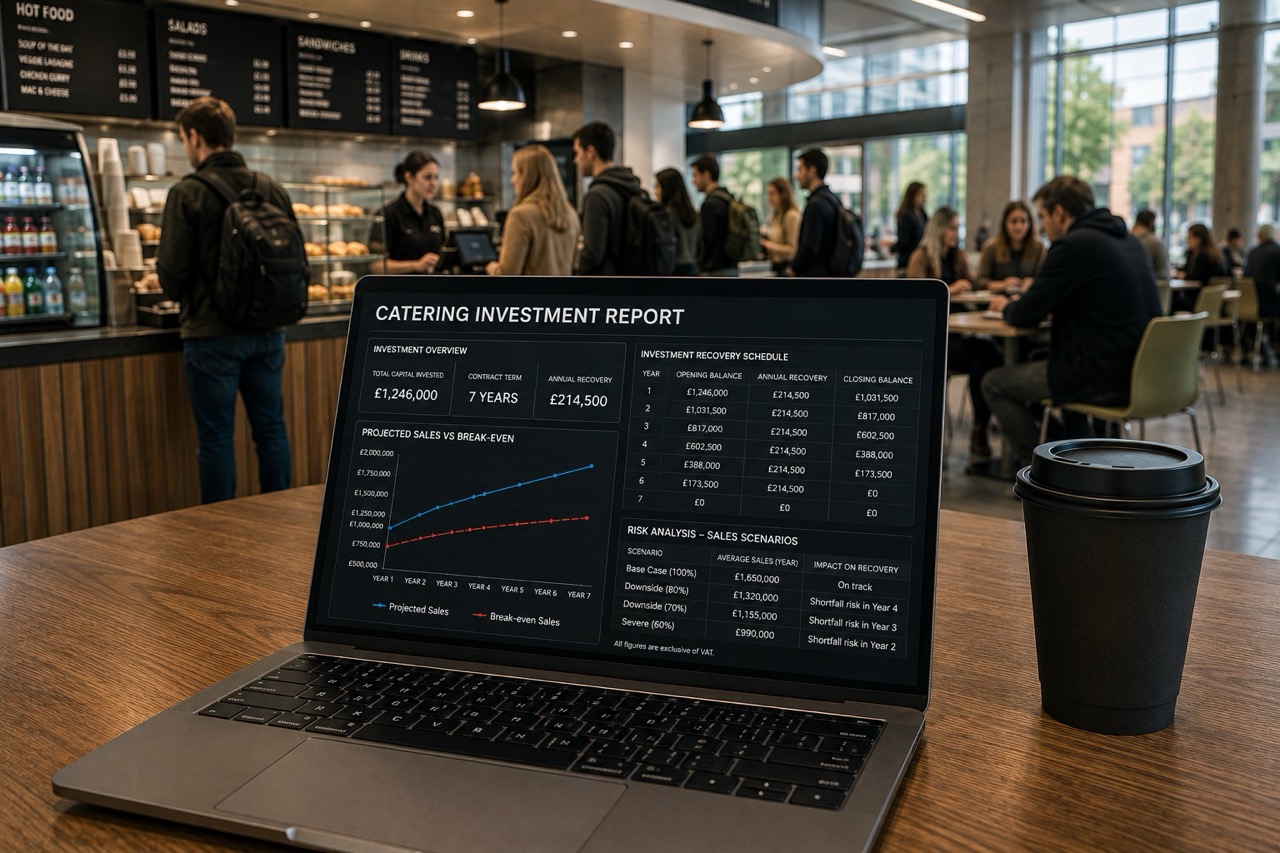
A transparent amortisation schedule should form part of the contract itself, showing the outstanding balance year by year across the full term, so that both parties can see at any given point what an early exit would cost. The financing rate implied by the recovery arrangements should be disclosed and, ideally, capped, and it should be compared explicitly against the client own cost of capital before the contract is awarded.
The sales forecast on which recovery depends should be stress tested before signature, and seventy to eighty per cent of the bid case is a reasonable starting point for that exercise. Where the model fails at that level of volume, the parties need to have agreed in advance what happens next, whether through volume banding, a risk sharing mechanism, an adjustment to the recovery profile, or a reduction in the scope of the investment itself.
Early termination arithmetic should be pre-agreed rather than negotiated under pressure at the point of maximum client weakness. Evaluation models deserve review for the incentives they create, because scoring that rewards the largest capital offer pushes bidders towards bigger investment, longer terms and more optimistic sales forecasts to support the recovery, which is close to the opposite of what a client organisation should actually want.
Finally, the volume assumption itself deserves to be the most heavily scrutinised number in any submission that includes contractor capital, because it is the number upon which everything else ultimately depends. In practice it is very often the least examined of them all, precisely because the capital offer resting on it is so attractive.
A wider point about facilities management
Catering is where this structure is most visible, but it is certainly not where it stops. Contractor-funded investment appears right across facilities management, in energy performance arrangements, in technology and workplace systems, in lifecycle funds within longer-term contracts, and increasingly in equipment-as-a-service models. In every one of those cases the underlying logic is the same, in that capital is advanced against a projected benefit and recovered over a term determined by the payback period rather than by the service requirement.
The question a client organisation should ask is always identical, whatever the service line involved. If the projected benefit does not arrive, who carries the difference, and what would it cost us to walk away. Organisations that can answer both parts of that question at the point of award tend to do rather well out of contractor-funded capital. Organisations that cannot are not really buying a service at all, but underwriting somebody else investment case without ever having seen the numbers behind it.
Is your FM contract delivering what it should?
Book a free discovery call with an EMC consultant. Evidence led, no obligation.
Book a call with EMC
Tell us a little about your FM arrangements and we will come back within one working day to arrange a time.